Home Insurance in Oklahoma City, OK
Welcome to the heart of the Sooner State. Living in our community means enjoying tight knit neighborhoods, wide open spaces just outside the metro, and a resilient, hardworking culture. But anyone who has spent a spring season here knows our beautiful home comes with famously unpredictable weather.
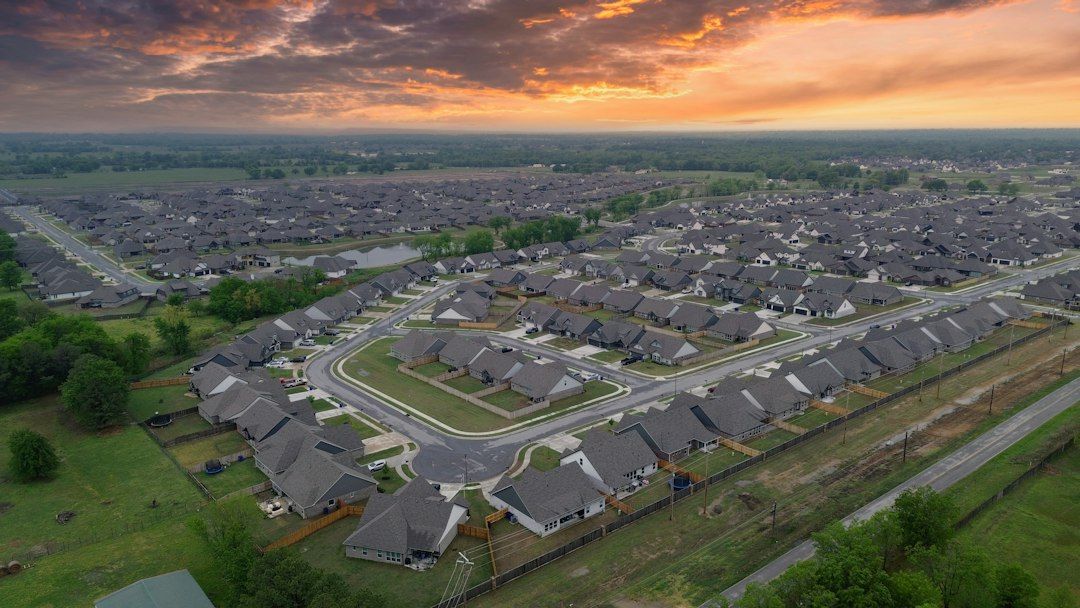
Protecting Your Oklahoma Masterpiece: A Local Guide to Property Coverage
Welcome to the heart of the Sooner State. Living in our community means enjoying tight knit neighborhoods, wide open spaces just outside the metro, and a resilient, hardworking culture. But anyone who has spent a spring season here knows that living in this beautiful area also means accepting our famously unpredictable weather. At the Cody Anderson Agency, we have spent over 30 years helping families, farmers, and business owners protect their most valuable assets. As a veteran owned business, supporting active duty service members, veterans, and local blue collar workers is deeply important to us.
Our mission has always been simple. We want to earn your trust, loyalty, and friendship by providing excellent service and being with you when it counts. Your house is likely your largest financial investment, and protecting it should never be left to guesswork. Whether you live in a historic neighborhood downtown or run a ranch on the rural outskirts of the metro, understanding the ins and outs of your property coverage is the first step toward true peace of mind.
The Reality of the Local Market
Let us face the facts straight away. Securing affordable home insurance in Oklahoma City, OK, is a frequent topic of conversation around kitchen tables and neighborhood block parties. Our state consistently ranks among the most expensive areas in the nation for property coverage, and the trends over the past few years have only amplified that reality.
The primary driver behind these rising premiums is our exposure to severe weather. From baseball sized hail to intense straight line winds and tornadoes, the storms that roll through our plains leave behind billions of dollars in property damage. According to a 2026 data analysis by Insurify, the average premiums in our state remain significantly higher than the national average. Insurers must price their policies to reflect the very real probability that they will need to pay out large sums for roof replacements and structural repairs after a major weather event.
Furthermore, the rising cost of building materials and skilled labor has dramatically increased the expense of rebuilding a house. A storm that caused ten thousand dollars in damage a decade ago might cost twice as much to repair today. Insurance companies adjust their rates to ensure they have the financial reserves necessary to rebuild your property at today's prices.
However, there is a silver lining. Despite these challenges, the Oklahoma Insurance Department confirmed in early 2026 that our state's insurance market remains highly competitive. This means that no single company dominates the landscape, and consumers still have the power of choice. Additionally, state programs like the Strengthen Oklahoma Homes grant initiative have been implemented to provide funding for homeowners to upgrade to storm resistant roofing. Lawmakers and regulators are actively working on legislative packages to strengthen consumer protections and stabilize the market.
Because the market is both expensive and competitive, shopping for Oklahoma City home insurance requires a strategic approach. It is not just about finding the lowest monthly payment. It is about understanding exactly what that payment guarantees when the storm clouds gather.
Key Aspects of Your Policy
When you sit down to review homeowners insurance in Oklahoma City, the terminology can feel overwhelming. Policies are broken down into several distinct categories of coverage. Understanding these core pillars will help you make informed decisions about your financial safety net.
Dwelling Protection
Dwelling coverage is the foundation of your policy. It pays to repair or rebuild the physical structure of your house if it is damaged by a covered peril like fire, wind, or hail.
The most critical factor here is ensuring your dwelling coverage limit matches your home's true replacement cost. Replacement cost is the amount it would take to hire contractors and buy materials to rebuild your house from the ground up right now. This is very different from your property's market value or its tax appraisal value. For our clients with custom built homes or specialized rural properties, we always emphasize the importance of calculating this figure accurately. We often recommend adding extended replacement cost coverage, which provides an extra buffer (often 20 to 50 percent above your dwelling limit) in case a widespread local disaster causes a sudden spike in the cost of lumber and labor.
Personal Property Coverage
If you took your house, turned it upside down, and shook it, everything that falls out is considered your personal property. This includes your furniture, clothing, electronics, and appliances.
A standard policy will cover these items, but you must pay close attention to how they are covered. We strongly advise opting for replacement cost coverage for your personal property rather than actual cash value. If a pipe bursts and ruins your five year old living room sofa, an actual cash value policy will only pay you what a heavily used sofa is worth today. A replacement cost policy will pay you enough to go out and buy a brand new sofa of similar quality.
Liability Protection
While severe weather gets all the headlines, liability risks can be just as financially devastating. If a guest slips on your icy driveway, or if your family dog bites a delivery driver, you could be held legally responsible for their medical bills and lost wages.
Personal liability coverage protects your assets by covering these costs, as well as your legal defense fees if you are sued. For individuals with significant assets, swimming pools, or large acreage, we often discuss increasing liability limits or adding an umbrella policy to provide an extra layer of financial security.
Tackling Weather Related Risks
When discussing home insurance in OKC, we have to spend time talking about wind and hail deductibles. Because wind and hail claims are so common here, most insurance companies separate the deductible for these specific perils from your standard all peril deductible.
Your all peril deductible (which applies to things like a kitchen fire or a burst pipe) is usually a flat dollar amount, such as one thousand or two thousand dollars. However, your wind and hail deductible is frequently calculated as a percentage of your total dwelling coverage. If your house is insured for three hundred thousand dollars and you have a two percent wind and hail deductible, your out of pocket cost before the insurance kicks in for a new roof would be six thousand dollars. Understanding this distinction is absolutely crucial so you are not caught off guard after a major spring storm.
Insights from a Local Expert
Over our three decades of serving this community, we have seen exactly what happens when policies are put to the test. Navigating the claims process after a massive storm can be incredibly stressful, which is why having a local advocate makes all the difference.
When you compare home insurance quotes in Oklahoma City, you are not just comparing prices. You are comparing the quality of the promise being made to you. One of the most significant trends we have observed over the past few years is how insurance companies are changing the way they handle roof claims.
Historically, most policies offered full replacement cost for roofs regardless of their age. Today, because of the staggering frequency of hail claims in our region, many carriers will only offer an actual cash value payout if your roof is older than ten or fifteen years. This means if a storm destroys your twelve year old roof, the insurance company will deduct a decade of depreciation from your payout, leaving you to cover thousands of dollars out of pocket. When we review policies for our clients, the roof payment schedule is one of the very first things we check. We believe in transparency, and we want you to know exactly how your roof is covered before the sirens sound.
Another insight we share with our clients is the importance of proactive documentation. Before storm season ramps up, take your smartphone and walk through every room of your house, slowly recording a video of your belongings. Open your closets, pan across your electronics, and film your garage tools. Upload this video to a secure cloud service. If a tornado or fire were to cause a total loss, having a visual inventory of your possessions makes the claims process significantly smoother and ensures you do not forget to claim valuable items.
We also understand the unique needs of our diverse community. For our active duty military clients who may be deploying or relocating, ensuring continuous and appropriate coverage for their property is a priority. For our farmers and ranchers on the outskirts of the metro, standard residential policies often fall short. We work closely with these clients to ensure outbuildings, specialized equipment, and unique liability exposures are properly addressed through our personal insurance options.
Smart Strategies to Optimize Your Premium
Knowing that homeowners insurance in Oklahoma City is a major line item in your household budget, we want to share several actionable strategies to help you manage your premium without sacrificing essential protection.
First, consider upgrading your home's defenses. If it is time to replace your roof, investing in Class 4 impact resistant shingles can be a game changer. While these materials cost more upfront, they are designed to withstand significant hail strikes. Many insurance carriers offer substantial premium discounts for homes with Class 4 roofs, and these savings can help offset the initial installation cost over time. Keep an eye on local and state grant programs that may help fund these resilient upgrades.
Second, consolidate your policies. Bundling your property coverage with your auto insurance is still one of the most effective ways to lower your overall insurance costs. Carriers want to earn all of your business, and they will typically offer a multi policy discount that can save you anywhere from ten to twenty percent across the board.
Third, review your deductibles thoughtfully. If you have built up a solid emergency savings fund, you might consider raising your flat rate all peril deductible from one thousand to two thousand or even two thousand five hundred dollars. Taking on slightly more of the initial risk translates to a lower annual premium. Just ensure you always have that deductible amount readily available in a liquid savings account.
Finally, do not set and forget your policy. Life changes, property values fluctuate, and insurance markets evolve. We recommend scheduling a brief review of your home insurance details every year or two. A quick conversation can uncover new discounts, highlight gaps in coverage, and ensure your policy is keeping pace with your life. You can always check our FAQ section for quick answers to common policy questions, but a one on one review is where the real value lies.
Conclusion
Owning a home in this part of the country comes with its own set of unique challenges, but the rewards of living in such a vibrant, tight knit community far outweigh the risks. The key to enjoying your home without underlying anxiety is knowing that you have built a strong, resilient financial safety net.
Finding the right coverage does not have to be an overwhelming chore. By understanding the core components of your policy, paying close attention to your wind and hail deductibles, and partnering with an agency that genuinely understands the local landscape, you can face storm season with confidence. You deserve a policy that works as hard as you do, backed by people who are deeply invested in your community.
Contact Cody Anderson Agency
When you’re ready for coverage that fits your life, business, or property, contact Cody Anderson Agency for a personalized insurance review today. Whether you’re a homeowner, rancher, business owner, active-duty service member, or veteran, we’re here with dependable guidance and protection when it counts.
We invite you to experience the difference of working with a local team that puts your needs first. To start the conversation and see how we can optimize your protection, get a quote on our homepage or reach out directly through our contact page. Let us earn your trust and help you secure the peace of mind you deserve.
By Cody Anderson & Team · Published 5/13/2026